 Aspire Review (2026)$0 a Month, You Pay on FX
Aspire is a fintech account (strongest in Southeast Asia), not a full bank — great for keeping fixed costs near zero on mostly-domestic activity, but confirm it supports your country and currencies before you build your finances around it.
Visit Aspire → Affiliate link — the rest of this page is the honest version, including who should skip it.
Watch the 2-minute review
Same honest take, in video form — from our YouTube channel.
⚡ Short on time? Watch the 30-second verdict Short.
Pricing (2026)
✓ Pricing re-verified 11 Sep 2026
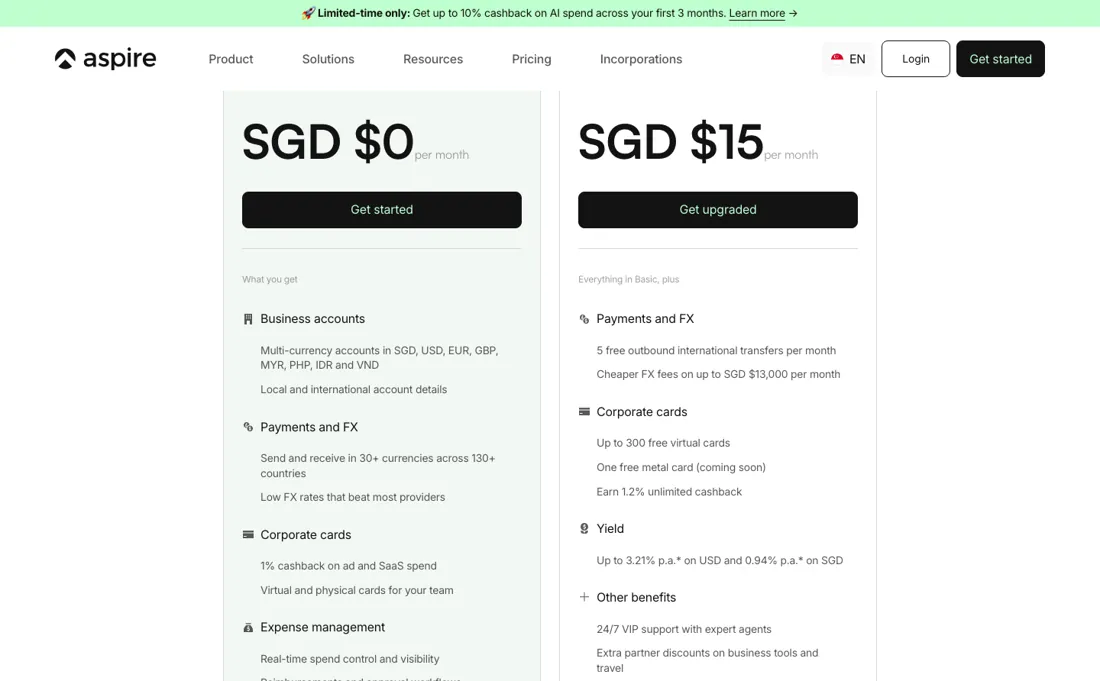
SGD $0 monthly fee on Basic, no minimum balance and no deposit to open. You pay per use: FX from 0.46% to send and from 0.34% to receive, inbound SWIFT SGD $35 for SGD accounts or USD $8 for others, outbound SWIFT USD $15 for SHA and USD $30 for OURS. Premium is SGD $15/month and zeroes the FX margin on the first SGD $13,000 of conversions a month, after which the same from-0.46% applies. Plans change — always verify the live price on their site.
What the price did
We capture Aspire’s own pricing page every month and keep the figures, so this is our record of the page — not a forecast, and not someone else’s summary.
Between our captures of aspireapp.com/pricing on 7 July and 2 August 2026 exactly one thing changed: the line "SGD $4 per additional spend user/month" was absent in July and present twice in August, once in each plan column. It was still there on 11 August 2026. Every other amount on the page - SGD $0 Basic, SGD $15 Premium, the SGD $13,000 zero-FX window, the SGD $35 / USD $8 inbound SWIFT fees - was identical in both captures. The 11 September 2026 read is the first that moved a rate: the send-side FX floor doubled from "From 0.23%" to "From 0.46%", on both Basic and Premium, while receive stayed at "From 0.34%" and instant conversion at "From 0.22%". The monthly fees, the SGD $13,000 window, the SWIFT fees and the SGD $4 spend-user line were all unchanged. The page also now prints outbound SWIFT fees (USD $15 SHA, USD $30 OURS) that it did not carry in our earlier captures.
Aspire’s pricing page, as we read it
What Aspire does
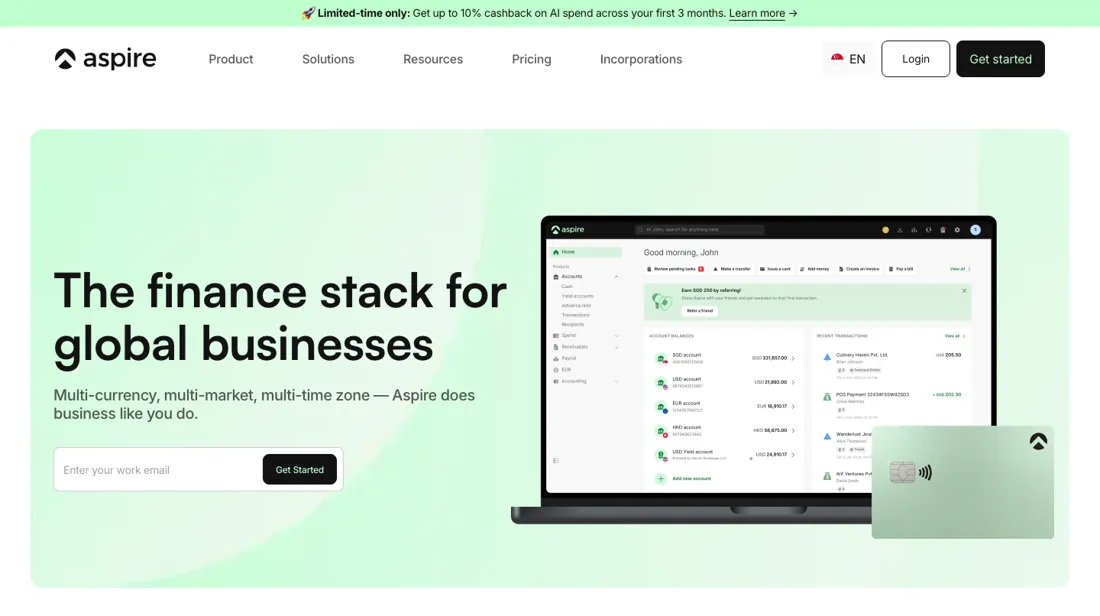
All-in-one finance stack for global businesses: multi-currency accounts (30+ currencies), corporate cards with 1.2% cashback, expense management, bill pay, payments and payroll — with AI fraud detection and multi-admin approval workflows.
What buyers report about Aspire
Recurring themes from the buyer-review sites listed at the foot of this page, read in August 2026. We have not run Aspire ourselves, so this is other buyers' experience rather than ours. We summarise it here because the complaints are usually the part a vendor page leaves out.
- • Onboarding with no paperwork is the recurring praise, particularly from first-time founders comparing it to a traditional bank.
- • For mostly domestic SGD activity the S$0 monthly fee and free local transfers do what they claim.
- • Sudden account closures and holds on funds, with little explanation, surface repeatedly across Trustpilot and Reddit. Compliance reviews triggered by regular payments to accounting and advisory firms are a specific recurring pattern. If your outgoings look like that, plan a fallback account.
- • Promotions carry terms in the fine print that reviewers say they did not expect.
- • Support experience is genuinely inconsistent — the same platform gets called both prompt and terrible in the same month.
When the paid plan is worth it
Aspire's Basic plan is SGD $0/month; Premium is SGD $15/month (Singapore/SGD pricing). Premium pays back if you send international transfers or convert FX regularly. It waives up to 5 outbound SWIFT transfers per month (the vendor values this at up to USD $75/month) and gives 0% FX on your first SGD $13,000/month of conversions, against a send rate starting at 0.46% on both plans. It lifts free spend users from 5 to 10 and free virtual cards from 200 to 300; beyond that either plan charges SGD $4 per additional spend user per month.
Cashback goes from 1% on ads and SaaS to 1.2% on all eligible spend, and the yield fee halves from 0.5% to 0.25%. What upgrading does NOT fix: the 0% window is capped at SGD $13,000/month and the send rate then reverts to the same from-0.46%; inbound SWIFT fees (SGD $35 / USD $8) still apply; and it adds no banking licence, lending or extra country coverage. If your activity is mostly domestic, Basic already costs nothing.
How to actually use Aspire
You sign up with a work email, verify by OTP, then pick your country of incorporation, industry, entity type and source of funds. You upload company documents through the app or web dashboard: an ACRA business profile for Singapore companies (Certificate of Incorporation plus Business Registration Certificate for Hong Kong ones), director ID or passport, proof of address, and a director facial verification. First login runs on OTP codes sent to both your email and phone, plus the ID number and birth date from registration.
The vendor advertises approval "as fast as 1 day," but a hands-on independent review reports 1–5 business days is more typical, stretching to 5–15 if a compliance review is triggered. Where people actually stall: document re-requests over mismatched names or expired certificates, an industry getting flagged higher-risk, unclear source-of-funds answers, and — per that same review — some accounts being paused months in with limited explanation. Answer document requests fast; slow replies extend the timeline.
Distilled from vendor docs (help.aspireapp.com first-login guide) and one hands-on independent review (growacross.com), which discloses several months of first-hand onboarding and usage.
The natural comparison is Wise Business or a local business bank — other multi-currency fintech accounts.
More on Aspire
Everything we publish about Aspire links back here — the review stays the honest hub:
The ex-banker filter — the same yardstick on every review (how we review): My ex-banker filter is simple: does Aspire remove a real cost — time, errors, missed revenue — bigger than what it charges?
Frequently asked questions
What does Aspire cost once more people need cards?
The monthly fee is the small part. Basic is SGD $0 a month and includes 5 free spend users; Premium is SGD $15 a month and includes 10. Beyond that the pricing page charges SGD $4 per additional spend user per month on both plans. That line is worth noting: it was not on the page when we captured it on 7 July 2026, and it was there on 2 August, on 11 August and again on 11 September.
What do the cards themselves cost?
Read from the vendor pricing page on 11 September 2026: physical cards are 1 free per user, then SGD $15 per additional card or equivalent; overseas ATM withdrawals are SGD $5 each, with a daily limit of USD $500 per card. Virtual cards are free up to 200 on Basic and up to 300 on Premium. Metal cards are listed at SGD $50 each with one free per account on Premium, but the page marks them "coming soon", so treat that as a promise rather than a card you can order today.
How long does approval actually take?
Aspire advertises approval "as fast as 1 day". The one independent hands-on review our dossier cites reports 1 to 5 business days as more typical, stretching to 5 to 15 if a compliance review is triggered. Where people stall is document re-requests over mismatched names or expired certificates, a higher-risk industry flag, and unclear source-of-funds answers. Answer document requests quickly; slow replies extend the timeline. That is their claim and one reviewer's experience, not our own onboarding.
What should I weigh before buying Financial Operations software?
The bar here is higher than features. Check who actually holds the money and under what licence, whether client funds are segregated, what audit trail and permission controls you get, and how support behaves when something goes wrong mid-transaction. Anything touching payments should be able to answer those in writing; if it cannot, that is your answer.
Is this a hands-on review of Aspire?
This is a researched assessment, not a hands-on test — where we've used a tool ourselves, we say so explicitly. We name what each tool is genuinely good and bad at, and we earn a commission only if you sign up, at no cost to you.
- Buyer reviews on Trustpilot, Statrys and Reddit, read August 2026.
- Price re-verified 2026-09-11 against the vendor's own pricing page.
- A dated screenshot of that pricing page, kept on this site as the receipt.
Others in this category
Reviewed financial operations tools that share ground with Aspire — comparable in what they do, not drop-in swaps:
New dossiers, cost-traps we found, and tools that earned a keep — no hype, no sponsored-disguised-as-advice. Unsubscribe anytime.
This is our researched assessment — not a paid placement. The “Visit” links on this page are affiliate links: we may earn a commission if you sign up, at no extra cost to you, and it never changes our take. How we review →